

Overview
- This article outlines the key factors that affect non-collateral business loan approvals, including financial performance, credit history, and proper documentation.
- It highlights the importance of steady revenue, a low debt-to-income ratio, strong credit scores, and consistent repayment history, along with complete records and a clear business plan to improve approval chances and secure funding.
Non-collateral loans help profitable businesses address cash flow gaps, fund expansion, and cover urgent expenses without risking assets. However, failing to meet key requirements can make approval difficult or prevent SMEs from securing financing altogether.
This is precisely why business owners must understand the factors that can affect non-collateral business loan applications. When they make themselves aware of potential pitfalls, they can take proactive measures to ensure they avoid complications when requesting funding.
Read on to learn which elements directly influence loan approvals and how to prepare for them effectively.
Financial Performance and Cash Flow
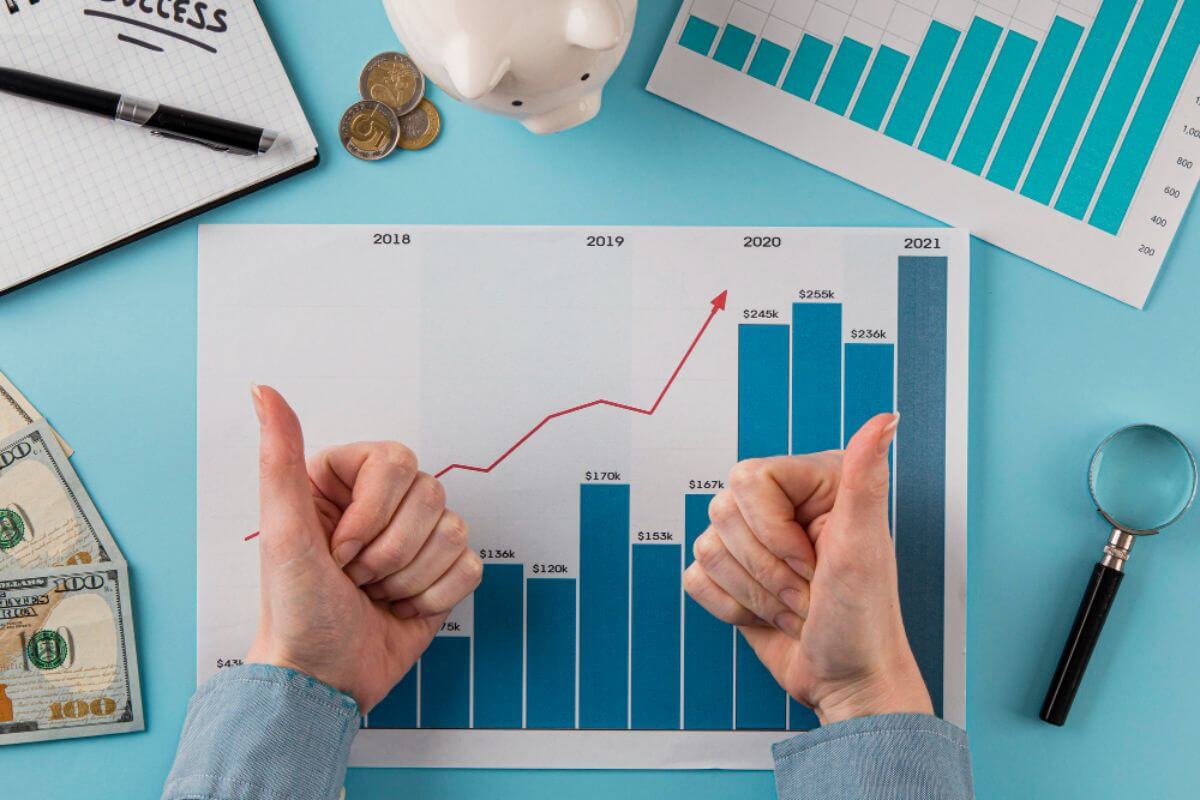
Your business’s financial health is the foundation lenders examine when reviewing non-collateral loan applications. Several financial metrics signal your repayment capability, and maintaining good records can influence approval decisions in a positive way.
Steady Revenue
Consistent revenue is a primary indicator lenders use to assess an SME’s ability to meet repayment obligations. They review bank statements, invoices, and financial records to verify steady income streams. Without predictable revenue, even profitable businesses may face challenges in securing the funding they need.
To demonstrate steady revenue, business owners can provide records of historical sales data or subscription income details. These help highlight periods of growth and present reliable client payments, reassuring lenders that they can effectively manage cash flow volatility. This transparency not only improves approval chances but also may result in more favorable loan terms.
Debt-to-Income Ratio
A low debt-to-income (DTI) ratio signals that a business is not overleveraged and can responsibly take on new financing. DTI measures the proportion of existing debt obligations that an SME may have relative to their total income, and lenders use it to assess whether the client has the repayment capacity to justify large funding.
Businesses with high DTI may struggle to qualify since additional debts could increase default risks. Operationally profitable SMEs with uneven income cycles can maintain a manageable DTI by prioritizing high-interest or short-term debts. By demonstrating their financial stability in this way, they can further strengthen funding partners’ confidence in their application.
Credit History
Since non-collateral funding relies heavily on a borrower’s creditworthiness, lenders tend to scrutinize credit scores and repayment patterns as their top indicators. This section explores how historical credit patterns impact your approval likelihood.
Credit Score
A strong credit score is a key factor in any loan evaluation. Lenders interpret high scores as a reliable sign of a business’s financial responsibility. When an applicant has a strong credit score, their likelihood of approval increases, and they can potentially benefit from lower interest rates.
SMEs should monitor both business and personal credit records carefully, as errors and outdated information can inadvertently flag suspicion among funding partners. Correcting discrepancies and ensuring accurate reporting are strong ways to showcase financial diligence, transparency, and commitment to repaying a loan.
Repayment History
Past behavior, including consistent on-time payments of loans, utilities, and supplier invoices, is used by lenders to predict a business’s future repayment reliability. If an SME’s records indicate consistently late payments, the financing partner may flag these irregular patterns as red flags and dismiss your application altogether.
Documenting timely payments and maintaining organized financial records can effectively help business owners mitigate concerns. Every business, regardless of its size or years in its respective industry, must showcase a track record of discipline in handling its debts.
Doing so reassures lenders that cash flow constraints will not affect repayment and, most importantly, that the borrowed amount is being used for meaningful expansion.
Documentation and Planning
Proper documentation and preparation demonstrate operational competence and show lenders that borrowed funds are being used to support key business growth opportunities.
Comprehensive Documentation
A small yet crucial detail that many lenders secretly assess is how well an SME documents its business’s financial information. Complete financial records, such as bank statements, tax returns, and profit and loss documents, are essential for lenders to verify financial performance. If certain documents are missing, it can lead to approval delays or even outright rejection.
Ensure that all records are up-to-date and clear of errors. Presenting comprehensive documentation conveys professionalism and reduces the lender’s perceived risks, which is especially important in loans where reputation and trust are used as security.
Thorough Business Plan
A clearly defined business plan that outlines the loan’s purpose, intended use of funds, and a detailed repayment strategy strengthens an application significantly. Lenders need to understand how the borrowed capital will drive growth and generate sufficient returns for repayment, so it’s important to go into a loan application with a solid plan.
For cash-flow-constrained SMEs, articulating strategies for bridging income gaps and planning for contingencies is a great way to showcase foresight. A solid business plan complements financial documentation, enhancing credibility and improving the likelihood of approval.
Apply For a Non-Collateral Business Loan Through Kredit Hero

Kredit Hero simplifies non-collateral business financing by using AI-driven assessments to match SMEs with suitable lenders, enabling them to compare offers, select flexible terms, and secure working capital in just a few clicks without giving up ownership.
Businesses can apply for a non-collateral business loan by following four easy steps:
- Fill out a quick online application with your business details and funding requirements
- Let our platform identify the lenders that suit your business’s needs
- Compare your loan options
- Wait for the lender’s approval
Key Takeaway
The factors that can affect non-collateral business loan applications go beyond basic eligibility and directly influence how lenders assess your risk and repayment capacity. Depending on how you manage your business’s finances, you can position your company for stronger chances of approval.
Through Kredit Hero, we connect SMEs to lenders best suited for their needs. Businesses can leverage our platform to navigate non-collateral loans and secure fast financing with confidence. Contact us today to get matched with a funding partner that suits your growth strategies.
Leave a Reply